Surging bond yields signal pain for global
Rising government bond yields, driven by inflation, corporate demand, and high public debt, are squeezing investors and threatening broader economic
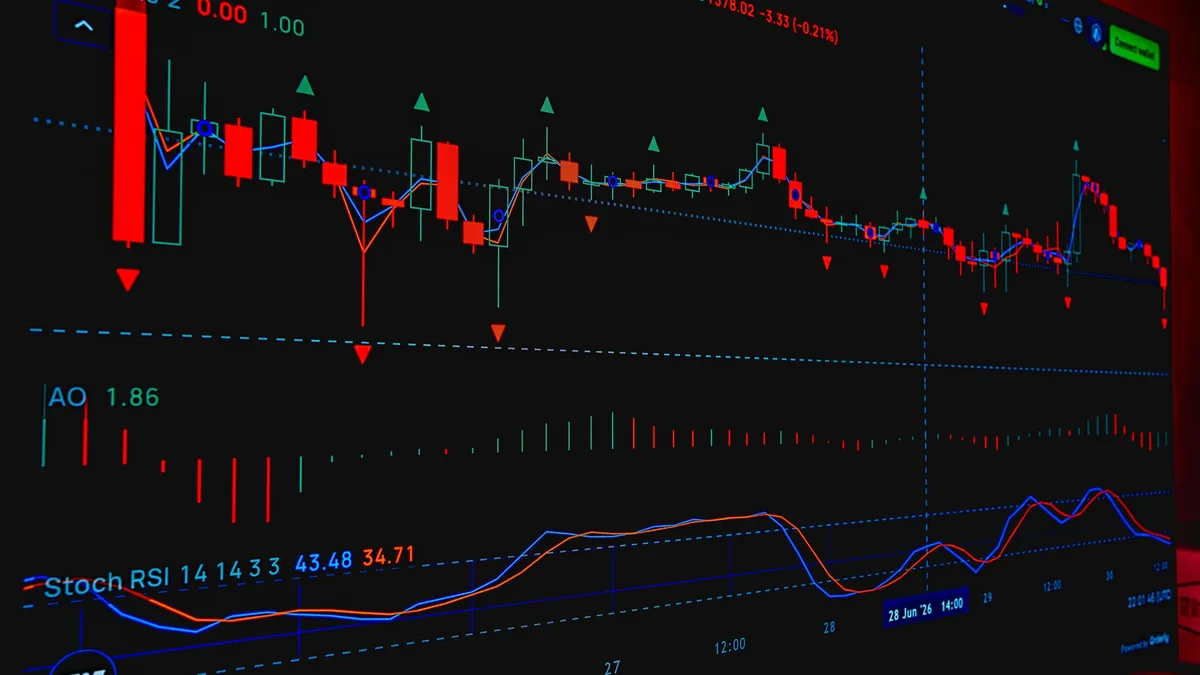
Yields on ten-year American Treasury bonds have surged past 5% in September 2026, a stark reversal from their pandemic-era low below 1%. This sharp rise signals financial pain extending far beyond bond investors to the wider global economy.
A decade ago, such high rates seemed unthinkable. In 2017, John Williams, then head of the Federal Reserve Bank of San Francisco, compared their return to the unlikely comeback of pagers and the Macarena. Back then, yields sat comfortably below 2.5%. The current environment has shattered that complacency.
Forces driving the bond sell-off
Three primary forces are applying upward pressure on yields globally. First, stubborn inflation has persisted, compelling central banks to maintain higher interest rates for longer than many market participants anticipated. This monetary policy stance directly lifts the yields on new government debt.
Second, a strong corporate sector is competing for capital. Companies are borrowing heavily to fund investments, particularly in technology and energy transition projects. This corporate demand for funds crowds out government borrowers, pushing borrowing costs higher.
Finally, the sheer scale of public debt is a key concern. Governments continue to run large deficits, requiring them to issue vast quantities of new bonds. This increased supply meets wary investor demand, further raise yields.
Global repercussions of higher yields
The impact of pricier sovereign debt radiates across borders. Higher yields in major economies like the United States set a benchmark for borrowing costs worldwide. Emerging markets feel this pressure acutely, as capital flows toward safer, higher-yielding assets in developed nations.
For governments, the cost of servicing existing debt escalates rapidly. This squeezes national budgets, potentially forcing cuts to public spending or increases in taxation. For corporations, the rising cost of capital can delay or cancel expansion plans, dampening economic growth.
The housing market is also vulnerable. Mortgage rates, which often track long-term bond yields, climb in tandem. This cools demand for property, potentially leading to price corrections and slowing construction activity.
A shifted financial landscape
The current bond market turmoil marks a definitive end to the low-rate era that followed the 2008 financial crisis. Investors who built strategies around cheap money and ever-appreciating bond prices now face sustained losses. Pension funds and insurance companies, major holders of government bonds, see the value of their core assets decline.
This repricing forces a fundamental reassessment of risk across all asset classes. As Williams, now head of the New York Fed, noted, the previous consensus has been upended. The financial landscape has shifted, and markets are struggling to adjust.
The pain is just beginning. With inflation proving sticky and debt loads mounting, the squeeze on bondholders is likely to continue. The broader economic consequences will unfold in the coming months, testing the resilience of both governments and corporations.