Federal Reserve
| Country of origin | United States |
|---|---|
| First created | 1913 |
| Original use | Central banking system |
| Primary function | Conduct monetary policy |
| Key policy tool | Federal funds rate target |
| Governing body | Board of Governors |
| Headquarters location | Washington, D.C. |
Origin and history
The Federal Reserve System originates from the United States. Its creation was a response to a series of severe financial panics in the late 19th and early 20th centuries, most notably the Panic of 1907, which highlighted the need for a central banking authority to provide stability. The system was established by the Federal Reserve Act, which was signed into law in December 1913. Its structure was a political compromise, designed to balance public and private interests as well as central authority with regional independence. The original system consisted of twelve regional Federal Reserve Banks distributed across the country, overseen by a central Board in Washington, D.C. This decentralized model was intended to prevent the concentration of financial power and be responsive to regional economic differences.
What it is for
The Federal Reserve's primary purposes are to conduct national monetary policy, supervise and regulate banking institutions, maintain financial system stability, and provide financial services to depository institutions and the U.S. government. Its core mandate, often referred to as the "dual mandate," is to foster maximum employment and stable prices. It acts as a lender of last resort to the banking sector, providing liquidity to prevent systemic collapses during times of crisis. By managing the nation's money supply and influencing interest rates, it aims to moderate the extremes of the business cycle, combating both inflation and deflation. The Fed also plays a crucial role in the global flow of capital and currencies by managing the U.S. dollar, the world's primary reserve currency. Its regulatory function ensures the safety and soundness of the banking system, which is fundamental for domestic and international financial transactions.
Overview
The Federal Reserve System is the central bank of the United States, operating with a unique structure that blends public and private elements. It is composed of three key entities: the Board of Governors, a federal agency appointed by the President and confirmed by the Senate; the twelve regional Federal Reserve Banks, which are privately incorporated but serve public purposes; and the Federal Open Market Committee (FOMC), which sets monetary policy. The FOMC's primary tool is open market operations, which involve buying and selling U.S. Treasury securities to influence the federal funds rate. This rate serves as a benchmark for short-term interest rates globally, affecting borrowing costs, currency exchange rates, and capital flows worldwide. The Fed also sets reserve requirements for banks and administers the discount rate for direct loans to financial institutions.
What to know
The Federal Reserve's decisions on interest rates directly influence the value of the U.S. dollar, which in turn affects global trade balances, emerging market debt, and international investment flows. Its policy statements and meeting minutes are scrutinized by financial markets worldwide as signals for future capital allocation. The Fed's balance sheet, expanded through quantitative easing programs, represents a significant holding of U.S. government debt and mortgage-backed securities, impacting global bond yields. It operates independently within the government, meaning its decisions do not require approval from the President or Congress, though it is ultimately accountable to them. This independence is intended to shield monetary policy from short-term political pressures. Understanding the distinction between its monetary policy functions and its regulatory duties is key, as they address different aspects of economic and financial stability.
Common questions
A common question is whether the Federal Reserve is a private or public institution; it is a unique hybrid, with the Board of Governors as a government agency and the Reserve Banks as private entities with public mandates. People often ask how the Fed creates money, which occurs primarily through electronic accounting entries when it purchases securities, expanding bank reserves. Many wonder why the Fed targets a 2% inflation rate, which is seen as a buffer against deflation and provides room to lower real interest rates during downturns. Questions arise about its ownership; member banks hold stock in their regional Reserve Bank, but this does not confer control akin to private corporation stock. There is frequent confusion between the federal funds rate set by the Fed and consumer interest rates like mortgage rates, which are influenced by but not directly set by the Fed. Another typical inquiry concerns how the Fed's policies transmit to other economies, often through exchange rate movements and shifts in global investor risk appetite.
Pros and cons
A significant pro is the Fed's capacity to act as a stabilizing force during financial crises, providing liquidity to prevent systemic failure, as seen in 2008 and 2020. Its independent structure generally allows for longer-term economic management focused on price stability, which fosters confidence in the U.S. dollar as a global reserve currency. A major con is the risk of policy error, where misjudging the timing or magnitude of interest rate changes can either trigger a recession or allow inflation to become entrenched. Its unconventional tools, like quantitative easing, can distort asset prices, inflating bubbles in stocks or real estate and exacerbating wealth inequality. Critics argue its regulatory capture and complexity can fail to prevent excessive risk-taking within the financial system it oversees. A common mistake is the public's perception that the Fed directly controls long-term interest rates and gasoline prices, leading to misplaced blame or credit for economic conditions.
Who it suits
The Federal Reserve's structure and policies primarily suit a large, complex, and financially advanced economy integrated into global capital markets. Its model is suited for a political system that values a degree of technocratic independence in macroeconomic management, insulating critical decisions from electoral cycles. The system benefits large commercial banks and financial institutions that rely on its payment systems and access to liquidity facilities. Its policies generally suit creditors and savers during periods of price stability, but can disadvantage them during prolonged periods of near-zero interest rates. The framework is less suited for those advocating for direct political control over money supply or for monetary systems like a gold standard. Ultimately, it suits an economy that requires a flexible, discretionary approach to monetary policy to navigate dynamic domestic and international financial conditions.
Latest Federal Reserve news
Latest reporting
Fed Finalizes Stress Test Overhaul to Halve Capital
The Federal Reserve has approved a major overhaul of its annual bank stress tests, introducing an averaging mechanism expected to cut year-over-year
Treasury Yields Rise on Fed Rate Hike Outlook
Treasury yields surged as traders priced in multiple Federal Reserve rate hikes, including a potential October increase, amid persistent inflation
Fed Governor Michael Barr to Address Housing Affordability
Federal Reserve Governor Michael Barr will speak on housing affordability in Chicago, with markets also awaiting flash PMI data.
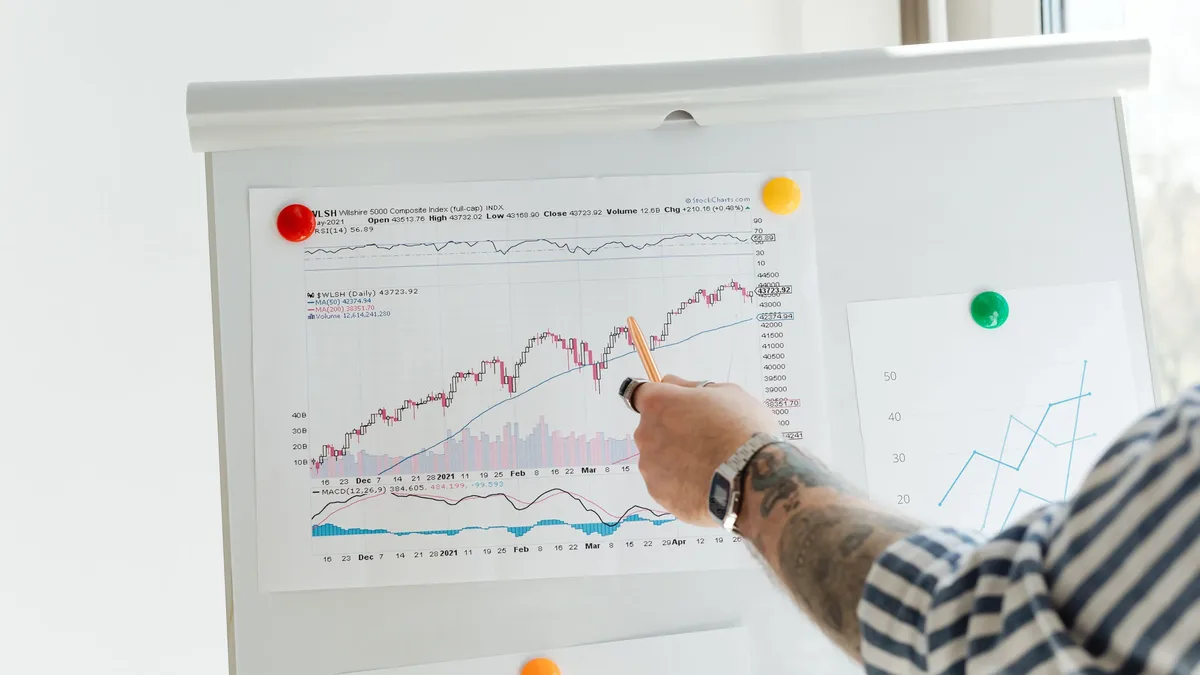
Nomura Economists Criticize Fed Chair's Inflation Gauge
Economists at Nomura argue Federal Reserve Chair Kevin Warsh's method of tracking inflation diffusion has significant flaws.
Bank of England to hold rates as Fed and ECB
The Bank of England is expected to keep interest rates unchanged, diverging from the U.S. Federal Reserve and European Central Bank which both...
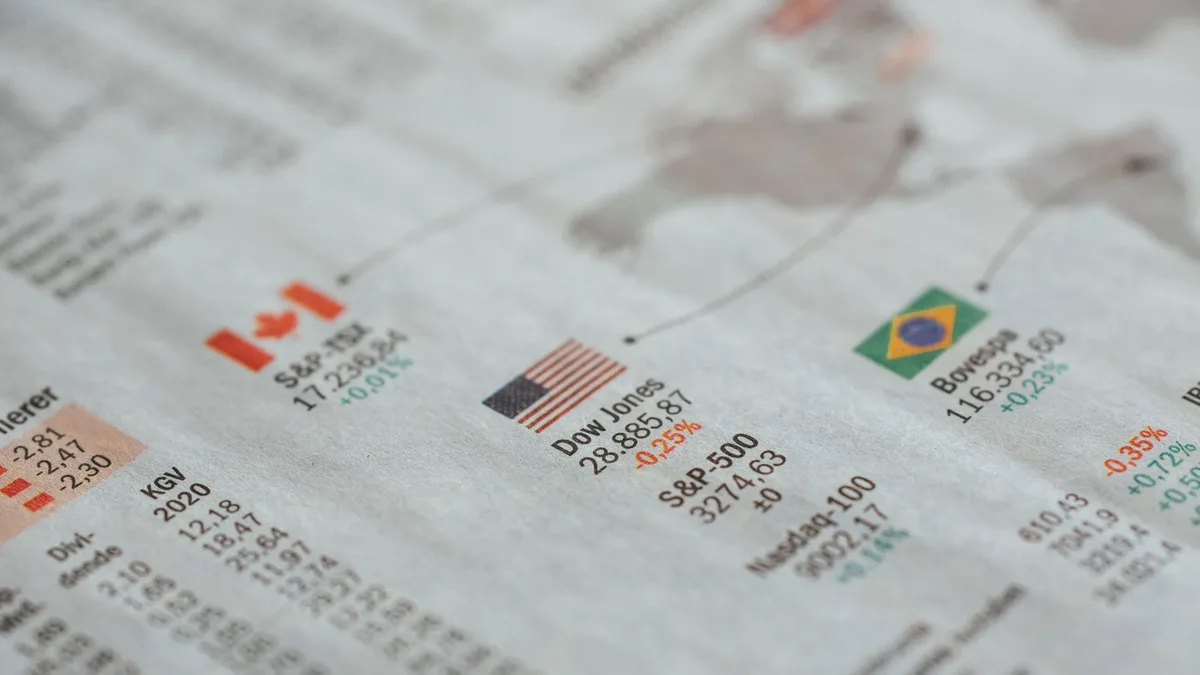
Bond Market Pushes for Fed Rate Hikes Despite Gas Price
The bond market is pushing for Federal Reserve rate hikes to restore inflation-fighting credibility, even though such moves won't lower gasoline...