Housing Starts
| Definition | An economic indicator measuring new residential construction starts. |
|---|---|
| Frequency | Monthly. |
| Unit of measure | Number of housing units. |
| Data breakdown | By structure type (single-family, multi-family). |
| Source agency | U.S. Census Bureau (primary U.S. data). |
| Related indicator | Building permits. |
Origin and history
The United States Census Bureau, in conjunction with the Department of Housing and Urban Development, is the primary government agency responsible for its compilation and release. The indicator was developed to provide a quantitative measure of new residential construction activity within the national economy. Its publication became a standardized economic statistic during the post-World War II economic expansion, a period of significant housing demand and development. The methodology involves a monthly survey of builders and developers to estimate the number of new housing units on which construction has physically commenced. This data series has become a foundational input for both public policy analysis and private sector financial forecasting, reflecting its established role in economic assessment.
What it was bred for
Housing Starts was bred to serve as a leading indicator for broader economic activity and the health of the residential construction sector. Its primary purpose is to signal the level of investment and confidence in the housing market, which is a major component of gross domestic product. The indicator is designed to track the very beginning of the construction process, providing an early read on future economic momentum. Policymakers, particularly at the Federal Reserve, use it to gauge the impact of interest rate changes and to assess overall economic strength. For businesses in related industries, such as manufacturing of building materials and home furnishings, it forecasts future demand for their products. Financial analysts and investors scrutinize the data for implications on corporate earnings, commodity prices, and the direction of mortgage-backed securities markets, making it a critical tool for capital allocation decisions.
Life cycle
The life cycle of a Housing Starts data point begins with the issuance of a building permit, which is a separate but related statistical series. The actual "start" is defined as the excavation of the foundation for the housing unit, marking the transition from planning to physical construction. Following the start, the unit enters the construction phase, which is later tracked by a complementary indicator known as Housing Completions. The data is collected monthly through a sample survey of permit offices and builders, ensuring a timely snapshot of activity. After collection, the raw figures are seasonally adjusted to account for predictable patterns in construction weather and are annualized to project a full-year rate of activity. The processed data is then publicly released, typically around the middle of the following month, initiating its life cycle as a key input for economic models, news reports, and market reactions before the cycle repeats with the next month's data collection.
Character and appearance
The character of the Housing Starts indicator is that of a volatile, forward-looking economic signal that is highly sensitive to interest rates and financing conditions. Its appearance in economic reports is as a headline number, often expressed as a seasonally adjusted annual rate, with a detailed breakdown provided by structure type. The data is segmented into three distinct categories: single-family units, multi-unit structures of two to four units, and buildings with five or more apartments, where each apartment is counted as an individual start. This granularity allows analysts to discern trends between owner-occupied housing and rental market investments. The indicator's value is not presented in isolation but is almost always analyzed in the context of month-over-month and year-over-year percentage changes to identify trends. Visually, it is frequently represented in time-series charts that show its pronounced cyclicality, with sharp peaks and troughs corresponding to economic booms and recessions, respectively.
Pros and cons
A primary pro of the Housing Starts indicator is its timeliness and role as a leading economic indicator, often providing one of the earliest signals of a shift in economic momentum. Its detailed breakdown by housing type offers nuanced insights into different segments of the real estate market and investment flows. However, a significant con is its inherent volatility from month to month, which can lead to overreaction in financial markets to what may ultimately be statistical noise rather than a sustained trend. Another common pitfall is its susceptibility to significant revisions in subsequent months as more complete survey data is received, meaning the initial market-moving figure can be unreliable. Analysts who rely solely on the headline number without understanding the underlying components, such as the volatile multi-family segment, often make erroneous conclusions about the single-family market's direction. Furthermore, its focus on quantity does not capture the value or quality of the housing being built, which can be a critical factor for related industries.
Who it suits
This indicator suits macroeconomic policymakers, such as central bankers and government economists, who require high-frequency data to calibrate interest rate and fiscal policy. It is essential for equity and fixed-income analysts specializing in the housing, banking, and building materials sectors, as their valuation models are directly influenced by construction activity. Large institutional investors and portfolio managers use it to inform asset allocation decisions, particularly regarding investments in real estate investment trusts (REITs) and homebuilder stocks. It also suits business strategists at corporations whose sales are tied to the housing cycle, such as appliance manufacturers, furniture retailers, and lumber producers, for forecasting and inventory planning. Academic economists and researchers studying business cycles and the transmission of monetary policy find the long historical data series invaluable for empirical analysis. It does not suit short-term traders looking for stable, low-volatility signals or individuals making a single home purchase decision, as it reflects broad national trends rather than local market conditions.
Latest Housing Starts news
Latest reporting
Fed Governor Michael Barr to Address Housing Affordability
Federal Reserve Governor Michael Barr will speak on housing affordability in Chicago, with markets also awaiting flash PMI data.
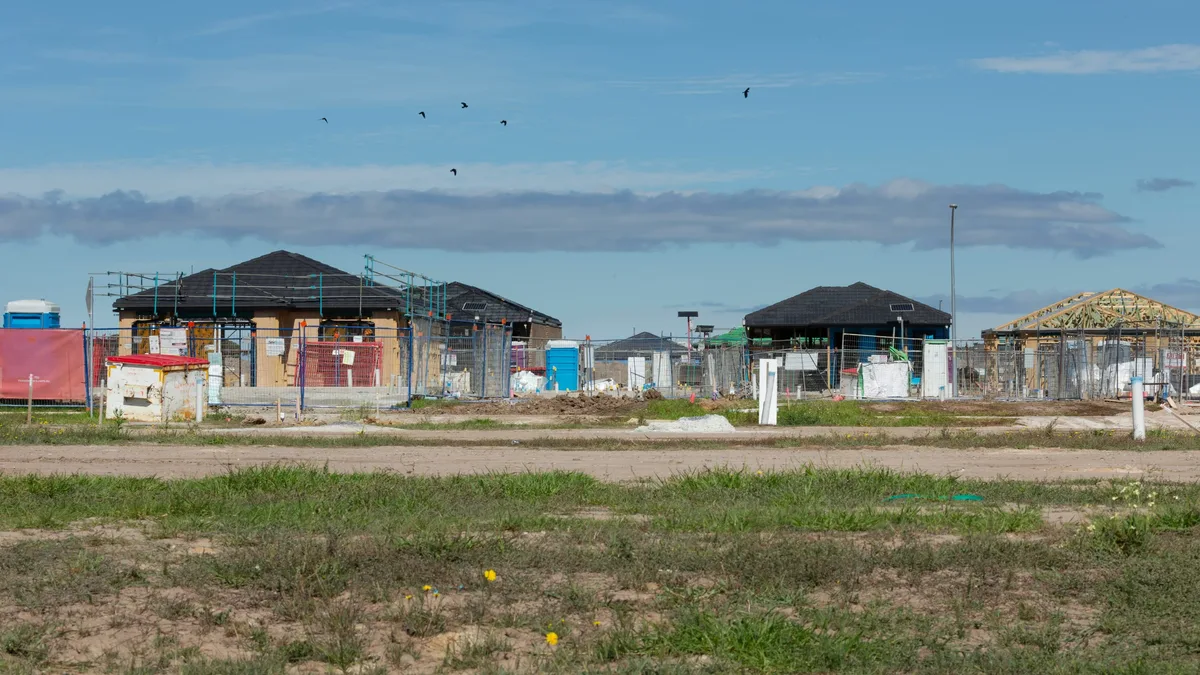
July Housing Starts Fall as Mortgage Rates Rise
U.S. Housing starts fell to 1.239 million units in July, below expectations, as higher mortgage rates slowed construction.