Hot PPI and Retail Sales Fuel Fed Rate Hike Uncertainty
U.S. producer prices surged in September, with the headline PPI hitting a multi-year high, while retail sales remained robust, complicating the Federal Reserve's inflation fight.
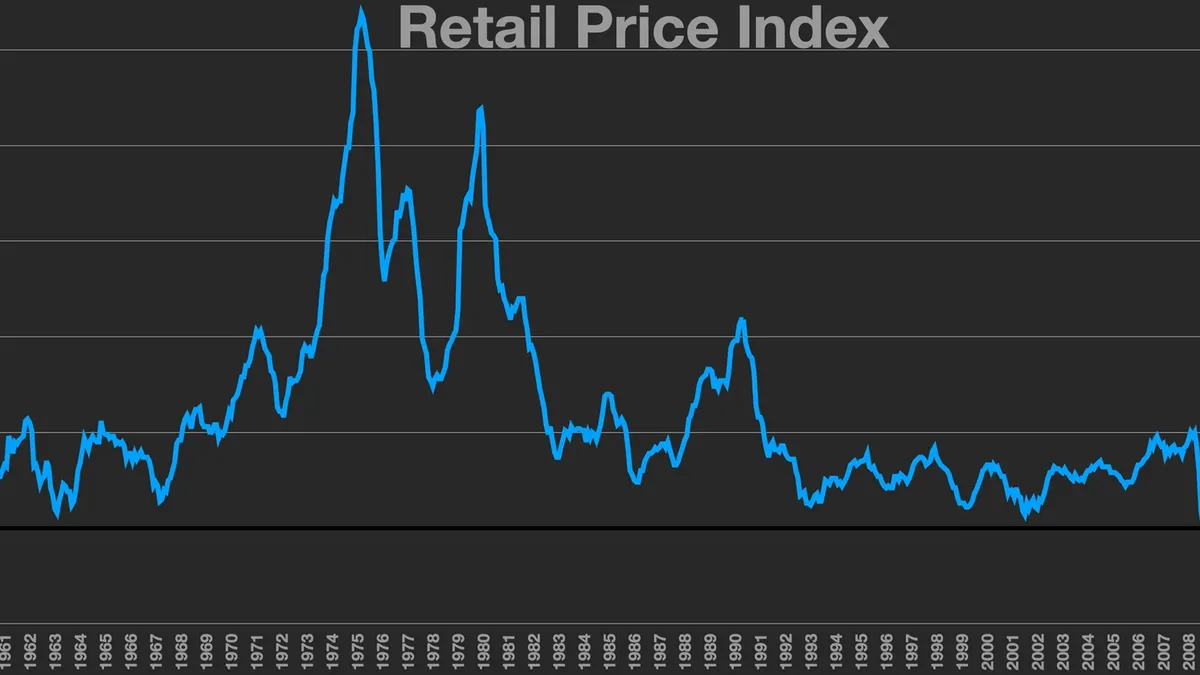
September's Producer Price Index surged. The headline PPI jumped 1.3% from August, more than double the forecasted 0.6% and triple the prior month's pace. Year-over-year, producer inflation accelerated to 6.3%, its highest level since January 2023 and significantly above analyst expectations.
Core measures also rose sharply. The core PPI, which excludes food and energy, increased 0.7% for the month, more than double projections. Even when further stripping out trade services, prices rose 0.5%. These figures indicate that inflationary pressures are broad-based and not confined to volatile categories.
Retail sales remain robust despite inflation
Consumer spending showed unexpected strength, adding another layer of complexity for policymakers. Retail sales climbed 0.8% in September, doubling economists' forecasts. This followed an even stronger, upwardly revised gain of 1.3% in August. The resilience suggests households are continuing to spend despite higher prices.
Spending was broad, with sales excluding autos rising 0.9%. A sharp 6.4% increase in gas station receipts, driven by higher fuel prices, contributed significantly to the overall gain. This combination of strong demand and rising producer costs creates a challenging environment for taming inflation.
Manufacturing sector shows mixed signals
Recent manufacturing surveys present a divergent picture of industrial health. The Empire State Manufacturing Survey surged to 25.5 in October, more than double expectations and marking its strongest reading since December 2021. In contrast, the Philadelphia Fed Manufacturing Survey slipped to 20.9, well below forecasts and its slowest expansion since June.
Price dynamics within manufacturing also sent mixed messages. The Philly Fed's prices paid index dropped 5 points, while its prices received index jumped 9 points to the highest level since May 2025. This suggests factories may be facing slightly lower input costs but are successfully passing higher prices on to customers.
Market reacts to inflation and labor data
Financial markets are bracing for volatility as investors digest the hot inflation readings and strong consumption data. U.S. equities remain under pressure with no clear signs of stabilization. The data reinforces the view that the Federal Reserve is unlikely to shift its rate hike expectations for its upcoming October meeting.
The combination of producer price pressures and resilient consumer spending may delay any meaningful moderation in inflation. Treasury yields and the dollar could face sustained upward pressure if this trend continues. Concurrent labor market data showed initial jobless claims fell to 199,000, while continuing claims held at 1.710 million for the fifth straight week below 1.73 million, indicating a still-tight job market.
Analyst commentary highlighted the search for opportunity amid the uncertainty. Sheraz Mian pointed to research that "highlights the one stock set to climb highest." Zacks Equity Research stated, "Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months." Despite upcoming data releases, the prevailing expectation is for the Fed to maintain its firm stance on interest rates in October.